 PIMFA





CONSUMER DUTY
The Consumer Duty is intended to ensure a higher standard of care across financial services for retail customers and to deliver good consumer outcomes throughout the life cycle of products and services.
The Consumer Duty is a significant regulatory change with a need for a shift in culture and mindset to focus on delivering good outcomes for retail customers. The Consumer Duty is subjective and requires a holistic approach: firms need to consider the application of the duty in line with their size, type and role within the distribution chain.
- Background and aim
The Consumer Duty aligns with the Financial Conduct Authority’s (FCA) business priorities focused on consumer outcomes and reducing and preventing serious harm. The FCA is increasingly focused on addressing consumer harms, particularly given the rise in customer vulnerability (as shown by responses to the FCA’s Financial Lives Surveys). The Consumer Duty intends to create a higher level of consumer protection in retail financial services, with the FCA highlighting their data-led and outcomes-based approach to supervision.
- ELEMENTS OF THE CONSUMER DUTY
- Consumer Principle 12 states that a firm must act to deliver good outcomes for retail customers.
- Cross-cutting rules state that firms must:
- Act in good faith toward retail customers
- Avoid causing foreseeable harm to retail customers
- Enable and support retail customers to pursue their financial objectives
- Products and services
- Price and value
- Consumer understanding
- Consumer support
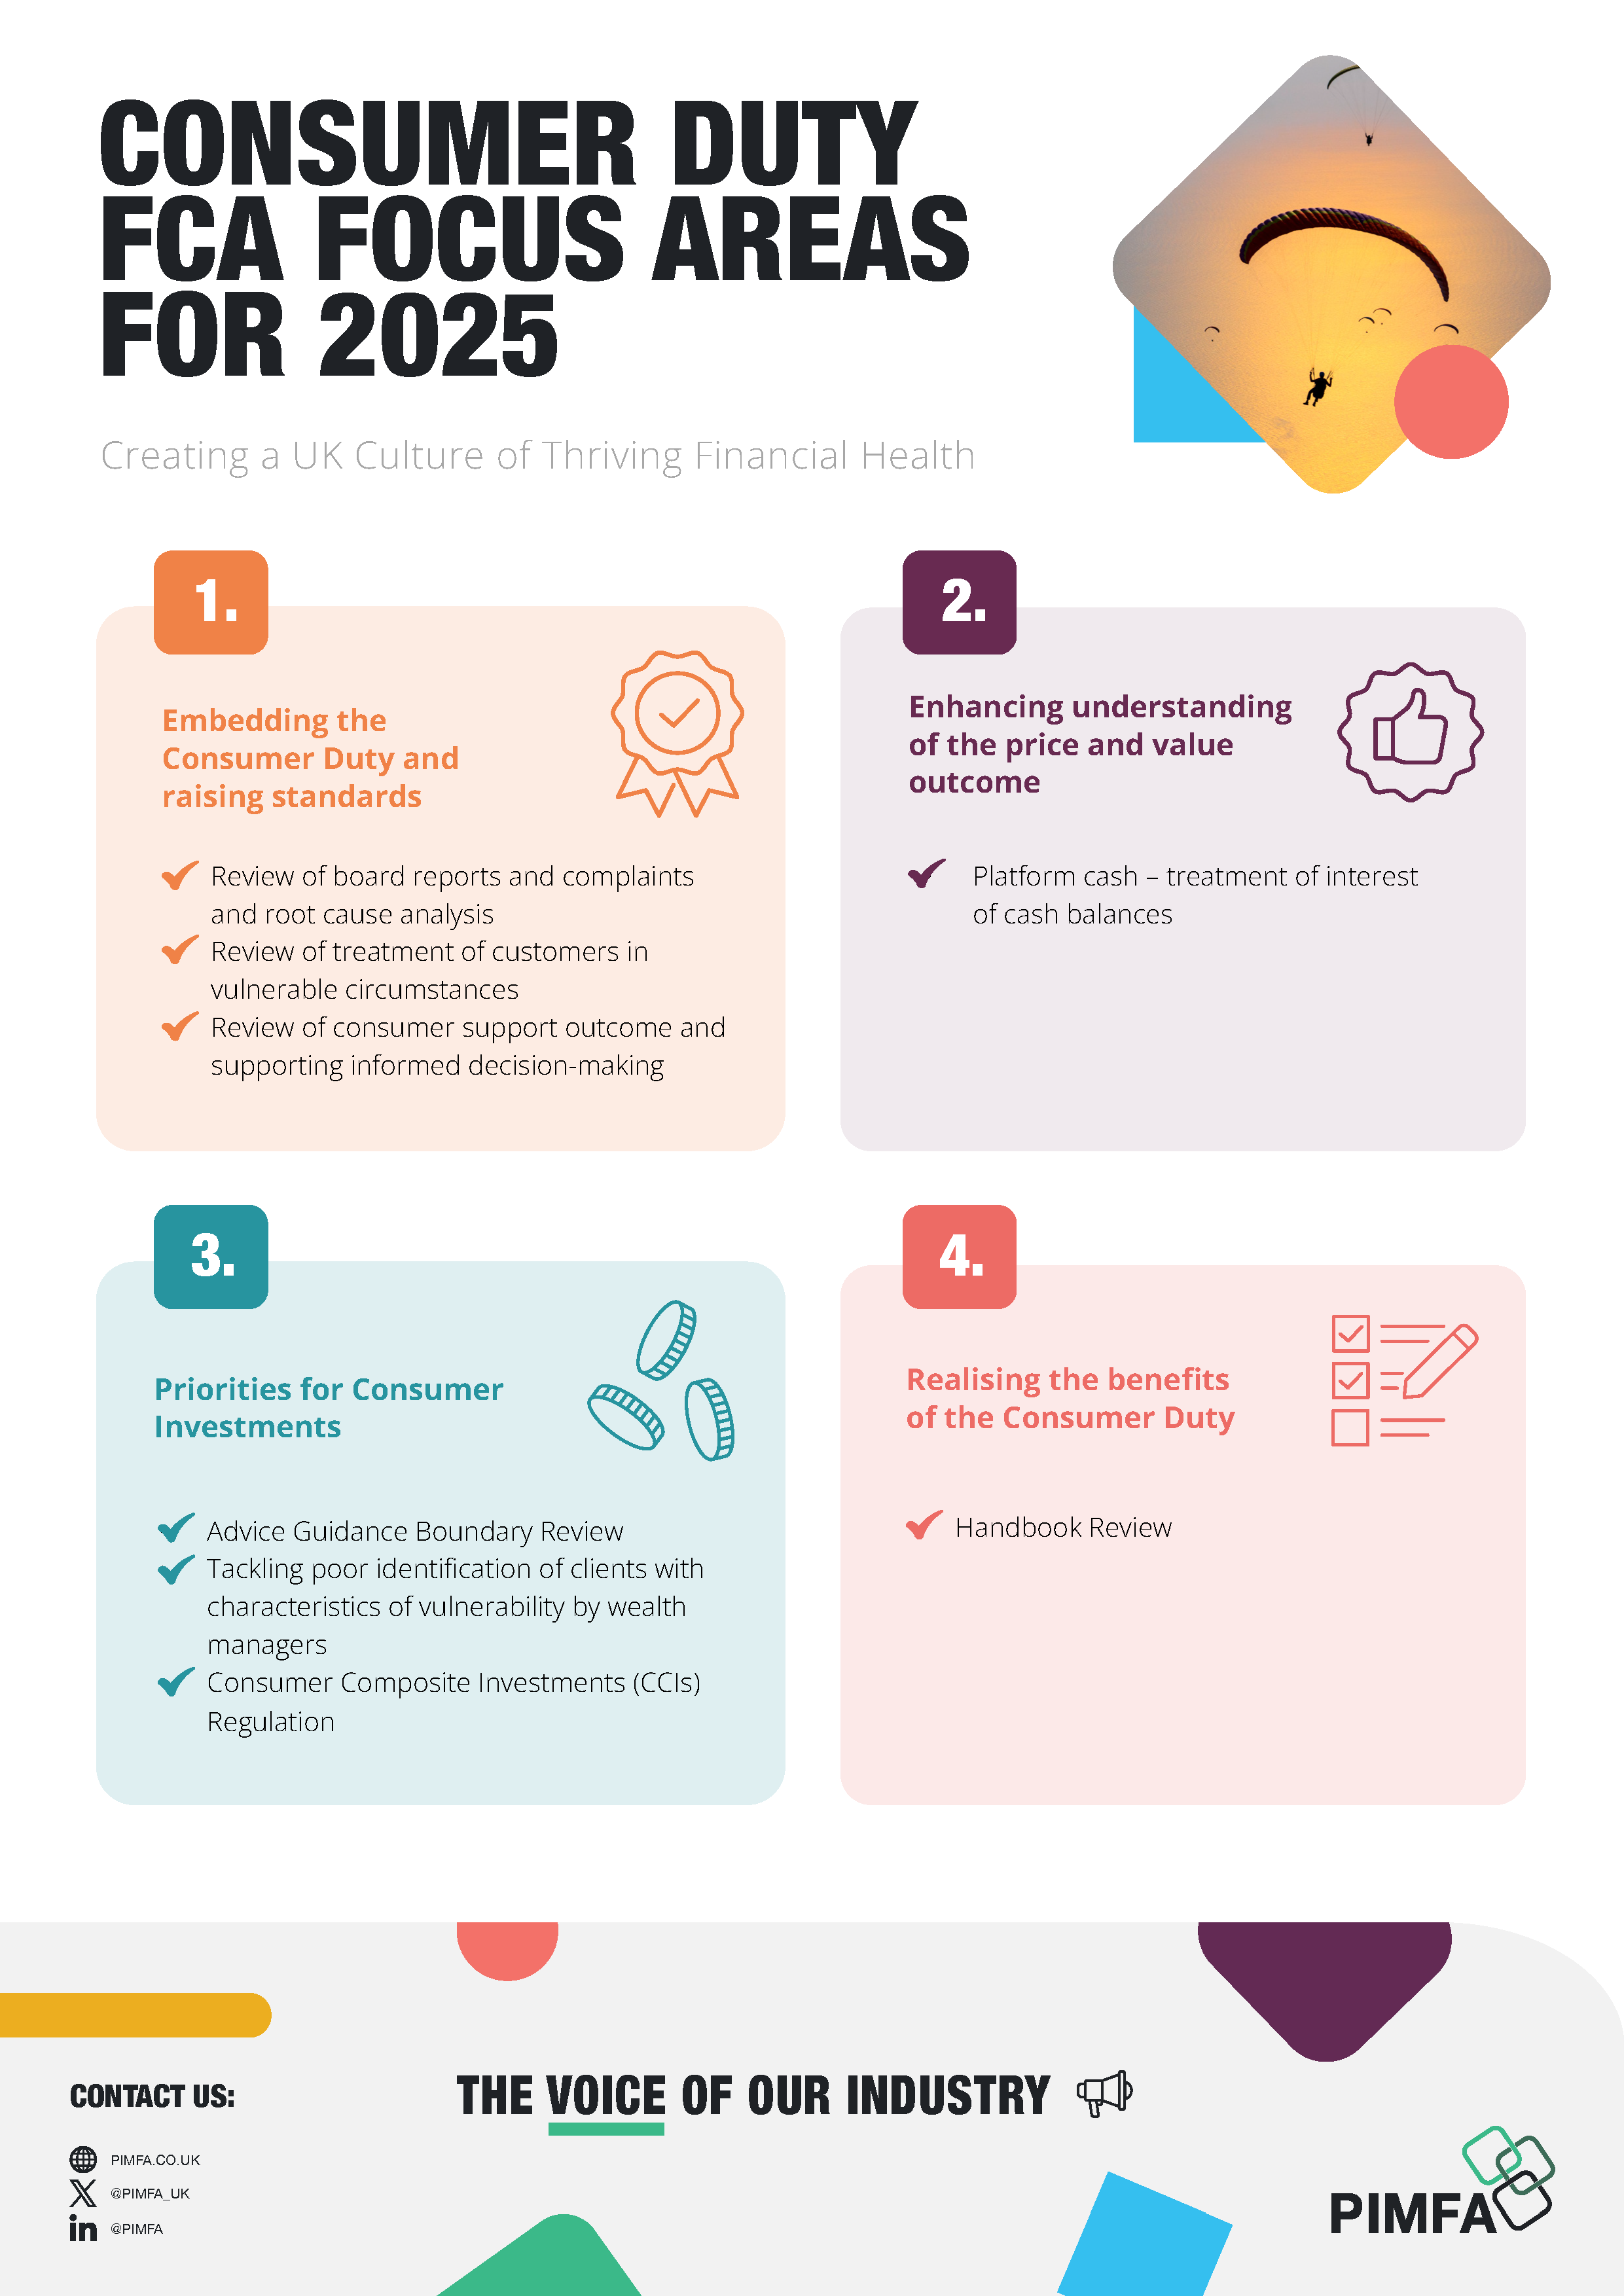
This report is free for our members and is available to purchase for non members.

latest news
FCA Contracts for difference firms: Good and Poor Practice Consumer Duty Price and Value Outcome
The FCA has published new findings following a May 2026 survey of 81 Contracts for difference (CFD) firms in light of the FCA’s multi firm review findings published in November.
This publication sets out good practices and areas for firms to consider in meeting their Consumer Duty price and fair value obligations.
Areas covered in the publication include fair value assessments, appropriateness testing and vulnerability monitoring, client disclosures and information, levels of charges and interest on cash balances.
Access the findings here
FCA Consumer Duty Requirements Review: Future Priorities Update
The FCA has published an update to its future priorities on its Consumer Duty webpage.
Read details here
A consumer focus on the Mills Review: What are the main consumer issues that you need to be thinking about?
A consumer focus on the Mills Review: What are the main consumer issues that you need to be thinking about?
FCA Findings: Market Study into the Distribution of Pure Protection Products to Retail Customers
The FCA has published findings (MS24/1.5) from the market study into the distribution of pure protection products to individual retail customers.
The FCA notes:
- That competition in the distribution of pure protection products generally works well for existing policyholders and delivers positive consumer outcomes
- Evidence of a protection gap due to a lack of consumer awareness, affordability and access issues
The report outlines measures aimed at reducing the protection gap with key elements including:
- Encouraging engagement, raising awareness and encouraging innovation
- A supervisory emphasis on product governance, Consumer Duty and fair value assessments
The importance of compliance with the Consumer Duty and PROD 4 requirements, in particular ensuring that the product, and how it is distributed and administered, delivers fair value is highlighted by the regulator.
Access the full report here
PIMFA response to FCA Consumer Duty Consultation (CP26-23)
PIMFA has welcomed the opportunity to respond to the latest FCA consultation on consumer duty scope and proportionality. The paper attempts to address some of the concerns that have been raised since the implementation of the duty. We are supportive of the intention to clarify and simplify the application of the regime. We have requested additional guidance and examples to support interpretation and remove the potential for further subjectivity.
Read the PIMFA response here